With sudden water damage from a leak, insurers often cover the resulting damage – and that frequently includes technical drying. What matters is the cause of the damage and the terms of your policy.
Which insurance applies?
For property in Spain this is usually a Spanish home insurance policy, the seguro de hogar, which can cover the building (continente) and contents (contenido). A UK home insurance policy normally won't cover a house in Mallorca. For apartments in a community, the community's building insurance may be responsible – for example if the water came from a shared pipe.
What is usually covered
- Damage from water escaping suddenly from fixed pipes or household appliances
- Often, finding the leak and repairing the affected section of pipe – provided it has caused damage to the property and the pipes belong to your home
- Putting right the resulting damage, which depending on the policy includes drying
What is often not covered
- Damage due to lack of maintenance or negligence
- Damage originating from a pool, well, water tank, irrigation or drains – depending on the policy
- Damp that builds up gradually, condensation or rising damp
- An excess (franquicia), if agreed
The evidence you need
- Photos and videos of the damage and its cause, before clearing up
- Prompt notification to your insurer within the deadline in your policy
- Invoices from the plumber and for the drying
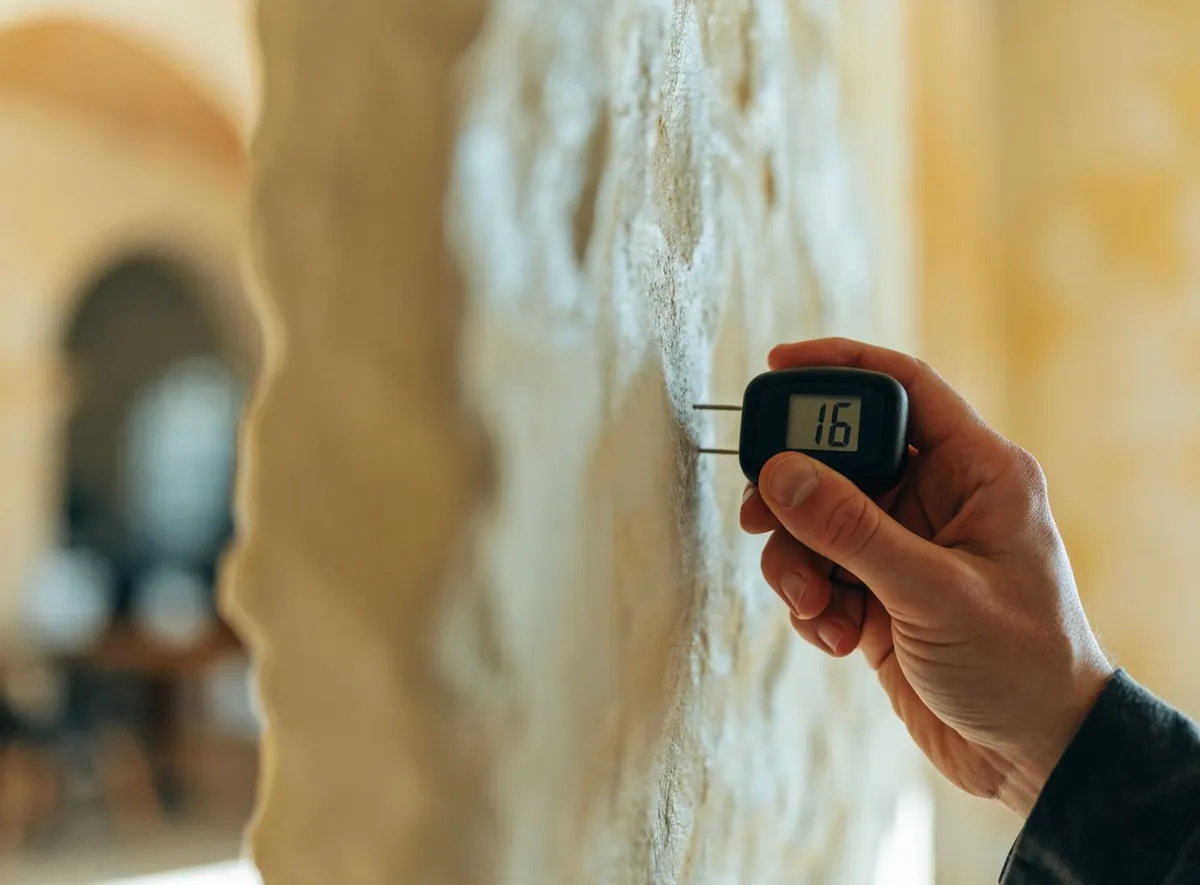
- A moisture report showing professional drying: measuring points, dated readings, units used, running times, final readings
Our report includes exactly that – in Spanish and German, so the Spanish loss adjuster (perito) can read it directly.
Our tip
Call your insurer before the drying starts and ask: Do you cover the drying? Are there requirements or a partner company? Will a loss adjuster come out? With those answers you're on the safe side.